NEW YORK — Many small businesses do not struggle because they lack customers. They struggle because sales, costs, invoices, taxes and financing move at different speeds, and the owner cannot see the gap until cash is already tight.
Better money management changes that.
It gives owners a clearer view of where revenue comes from, which products or customers are truly profitable, when bills will come due, how much cash is available for payroll or inventory, and whether the business can afford its next step.
The goal is not to turn every entrepreneur into an accountant. It is to give owners enough financial control to make growth decisions based on evidence rather than instinct.
The Internal Revenue Service says good business records help owners monitor progress, prepare financial statements, identify income sources, track deductible expenses, prepare tax returns and support the figures reported to the government.
For a growing business, the same records can answer more strategic questions: Can we hire? Should we raise prices? Which marketing channel is producing profitable customers? Can we open a second location? Is our best-selling service actually making money?
The answers often begin with disciplined cash management.
Revenue is not cash
One of the most important money-management lessons is that revenue does not equal cash in the bank.
A company can make a sale today but not collect payment for 30, 60 or 90 days. Meanwhile, it may need to pay employees, suppliers, rent, software subscriptions, taxes and loan payments immediately.
That gap is cash flow.
A profitable business can still fail if it cannot meet obligations when they are due. Conversely, a business with temporary cash reserves can survive a slow month long enough to correct a problem.
The basic calculation is:
Net cash flow = Cash received − Cash paid out
When the number is positive, cash increases. When it is negative, the business is using more cash than it brings in.
This formula is simple. Managing it is not.
Consider a home-remodeling contractor that signs $100,000 in new projects. The business may appear healthy. But if it must buy materials and pay subcontractors before clients make progress payments, it may face a short-term cash shortage despite strong sales.
The solution is not necessarily to reject the work. It is to understand the timing:
- When will deposits arrive?
- When are materials due?
- When will labor costs hit?
- Are clients paying on schedule?
- Is a line of credit available if necessary?
- Does the business have enough reserve cash to absorb a delay?
That is why cash flow should be reviewed weekly or at least monthly, not only at tax time.
Separate personal and business money
A basic but essential step is separating business finances from personal finances.
Owners should use a dedicated business checking account, business credit card and accounting system. Mixing personal spending with business transactions makes it harder to understand performance, prepare taxes, demonstrate profitability to lenders and spot unauthorized activity.
It can also create legal and administrative complications depending on the business structure.
The SBA’s business guidance advises owners to open a business bank account as part of launching and managing a company.
Separate accounts create clearer records for:
- Customer payments.
- Supplier and contractor expenses.
- Payroll.
- Taxes.
- Loan payments.
- Owner draws or salary.
- Marketing costs.
- Equipment purchases.
- Insurance.
- Recurring subscriptions.
The habit also creates discipline. If an owner needs to take money from the business for personal use, it should be recorded clearly as an owner draw, salary or distribution, not hidden among ordinary operating expenses.
That distinction matters when evaluating whether the business is genuinely profitable.
Read the three essential statements
SCORE describes the profit-and-loss statement, balance sheet and cash-flow statement as the three core financial statements that together show how a business performs, what it owns and owes, and whether it can sustain its current trajectory.
Every owner should understand the basics.
Profit-and-loss statement
The profit-and-loss statement, often called an income statement or P&L, shows revenue minus expenses over a period of time.
It answers: Did the business make a profit?
Revenue − Cost of goods sold − Operating expenses = Net profit
The P&L helps identify whether pricing is adequate, which costs are increasing and whether growth is translating into profit.
But it does not necessarily show cash timing. A sale can appear on a P&L before the customer pays.
Balance sheet
A balance sheet is a snapshot of the business at a specific date.
It shows:
Assets = Liabilities + Owner’s equity
Assets include cash, inventory, equipment and money owed by customers. Liabilities include loans, unpaid bills, payroll obligations and taxes due.
The balance sheet answers: What does the business own, what does it owe, and what is left for the owner?
Cash-flow statement
A cash-flow statement tracks money moving into and out of the business through operations, investing and financing.
It answers: Can the business pay its bills?
A company can have a strong P&L but weak cash flow if customers are slow to pay or if it spends heavily on inventory or equipment.
These statements should not sit untouched in accounting software. They should guide decisions.
SCORE says financial statements offer the most honest feedback a business can receive: They show where money is made, where it is lost, which customers and products are worth keeping, and whether growth is sustainable.
Build a cashflow forecast
A cash-flow forecast is one of the most useful tools a small business can create.
It estimates future inflows and outflows, helping owners identify potential shortfalls before they become emergencies.
A simple forecast can cover the next 13 weeks or the next six to 12 months. The shorter version is useful for immediate cash decisions; the longer version helps plan hiring, expansion and financing.
A basic weekly forecast should include:
| Cash inflows | Cash outflows |
|---|---|
| Customer invoices expected to be paid | Payroll |
| Sales receipts | Rent and utilities |
| Deposits and retainers | Inventory and materials |
| Loan proceeds or owner contributions | Loan payments |
| Tax refunds or credits | Taxes |
| Other operating income | Insurance, software and subscriptions |
| Marketing and contractor payments |
The key is to be conservative.
Do not assume every invoice will be paid on time. Do not assume every sales lead will close. Do not ignore annual insurance bills, tax deadlines, equipment repairs or slow seasons.
A business owner who sees a projected cash shortage six weeks ahead has options. They can accelerate collections, delay a nonessential purchase, negotiate payment terms with a supplier, use a credit line thoughtfully or adjust staffing. An owner who discovers the shortage after payroll is due has far fewer choices.
Manage accounts receivable aggressively but professionally
Unpaid invoices are one of the most common causes of cash stress.
A sale is not complete from a cash-management perspective until payment arrives.
Businesses can improve collection by making payment easy and expectations clear:
- Require deposits or retainers for large projects.
- Invoice immediately after work is completed or at defined milestones.
- Include payment terms clearly in contracts.
- Offer online payment options.
- Send polite reminders before the due date.
- Follow up promptly after a missed deadline.
- Stop additional work when overdue balances exceed an agreed threshold.
- Review customer creditworthiness for large or recurring accounts.
The objective is not to alienate customers. It is to establish a predictable process.
For project-based companies, milestone billing can be especially important. Instead of waiting until the end of a large job, the business can collect part of the revenue at signing, part after a deliverable and the remainder at completion.
That reduces the chance that the company finances a client’s project out of its own pocket.
Know your margins before you grow
Not every dollar of revenue is equally valuable.
A business may sell a high volume of a product with thin margins while ignoring a lower-volume service that generates much more profit. Growth without margin discipline can increase workload and cash pressure without improving the owner’s financial position.
Gross margin measures how much money remains after direct costs:
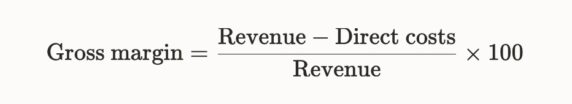
Direct costs can include materials, shipping, production labor, wholesale inventory, sales commissions or contractor payments directly tied to a sale.
For example, if a product sells for $200 and costs $120 to purchase, prepare and ship, the gross profit is $80 and the gross margin is 40%.
The business must still use that $80 to cover rent, payroll, marketing, taxes and other overhead. If margins are too low, more sales may not solve the problem.
Owners should review margins by:
- Product.
- Service line.
- Customer type.
- Sales channel.
- Project.
- Location.
- Season.
That analysis can reveal difficult but valuable truths. A customer who generates a lot of revenue may require so much support, discounting or custom work that the relationship is not profitable. A service that seems secondary may be the business’s best source of margin.
Money management turns those observations into action: raise prices, negotiate supplier costs, reduce waste, discontinue an unprofitable offering or focus marketing on the highest-value customers.
Budget for growth and taxes
A budget is not a punishment. It is a plan for using money intentionally.
The budget should distinguish between:
- Fixed costs: Rent, insurance, salaries, loan payments and core software.
- Variable costs: Materials, commissions, shipping, contractor expenses and some marketing.
- Growth investments: New equipment, staff, advertising, training, technology or inventory.
- Taxes: Income taxes, sales taxes, payroll taxes and estimated payments.
- Reserves: Cash set aside for emergencies and slow periods.
A strong budget does not assume that revenue will rise forever. It prepares for uneven months.
Tax planning deserves special attention. Many owners make the mistake of treating all available cash as spendable, then face a tax bill they did not reserve for.
The IRS says a business recordkeeping system must clearly show income and expenses. Supporting documents such as purchases, sales, payroll records and other transactions provide the information needed to record activity in the business books.
The right tax strategy depends on the business structure, location, deductions, payroll responsibilities and other factors. Owners should work with a qualified tax professional rather than rely on generic online advice.
But the operational principle is universal: set aside tax money as revenue arrives, not after it is spent.
Create controls before growth creates risk
Better money management is also fraud prevention.
As businesses grow, more people may handle invoices, deposits, reimbursements, vendor records and payment approvals. Without controls, errors or misuse can go unnoticed.
SCORE recommends internal financial controls to reduce the risk of fraud, cash-flow problems and business failure.
Basic controls include:
- Require approval for payments above a set threshold.
- Separate the person who approves invoices from the person who pays them where possible.
- Reconcile bank and credit-card accounts every month.
- Review vendor bank-detail changes by phone using a verified number.
- Limit access to payroll, banking and accounting systems.
- Use multifactor authentication.
- Save invoices, receipts and contracts in organized digital folders.
- Review recurring subscriptions and automatic charges quarterly.
- Compare actual spending with budgeted spending every month.
These practices may sound bureaucratic for a small company. In reality, they protect the flexibility small companies need.
A single fraudulent payment missed tax deadline or unrecognized expense can cause outsized damage when resources are limited.
Use debt strategically, not emotionally
Debt can help a business grow. It can finance equipment, inventory, a new location, a vehicle or a contract that produces more revenue than the financing costs.
But debt is dangerous when used to cover a recurring operating shortfall without a clear path to improvement.
Before taking a loan or opening a credit line, owners should ask:
- What specific use will the money fund?
- What return will it produce?
- When will the investment generate cash?
- Can the business make payments if sales fall 20%?
- Is the interest rate fixed or variable?
- What collateral or personal guarantee is required?
- Are there prepayment penalties or restrictive covenants?
- Is there a less expensive alternative?
Debt should support a plan, not substitute for one.
A restaurant using a short-term loan to buy equipment that lowers labor costs may have a clear return on investment. A business using high-interest debt every month to cover payroll may have a pricing, collections or cost-control problem that borrowing alone will not fix.
Build reserves before you need them
Every business faces surprises: a late-paying customer, a broken vehicle, a supplier disruption, an insurance claim, a sudden drop in demand or an emergency repair.
Cash reserves provide time to respond without immediately turning to high-cost debt.
The appropriate reserve varies by industry. A business with steady subscription revenue may need a smaller buffer than a seasonal retailer, construction firm or hospitality company facing volatile costs.
A practical starting target is one month of core operating expenses, then two months, then three months or more as the business becomes stronger.
The reserve should be held in an accessible, low-risk account, not in speculative investments or money needed for day-to-day operations.
A reserve does not mean a business is pessimistic. It means the owner is protecting the ability to make decisions calmly when conditions change.
A monthly money-management routine
Good financial management becomes powerful when it is routine.
A monthly financial meeting, even if the business has only one owner, can create discipline.
Weekly
- Review bank balances.
- Review invoices due and overdue.
- Update the 13-week cash forecast.
- Check upcoming payroll, tax and supplier obligations.
- Watch for unusual spending or suspicious payment requests.
Monthly
- Reconcile bank and credit-card accounts.
- Review the P&L, balance sheet and cash-flow statement.
- Compare actual results with the budget.
- Review profit margins by product, service or customer.
- Set aside taxes and reserves.
- Review debt balances and interest costs.
- Identify one corrective action for the next month.
Quarterly
- Revisit pricing.
- Review customer concentration risk.
- Audit subscriptions, suppliers and recurring expenses.
- Meet with a bookkeeper, accountant or advisor.
- Assess whether the business can afford planned hiring, equipment or expansion.
- Update the annual forecast.
The routine should lead to action. If a report shows margins shrinking, decide whether to raise prices, renegotiate costs or stop selling a weak product. If accounts receivable rise, improve billing and follow-up. If cash reserves are too low, delay a discretionary purchase and rebuild the buffer.
Get help before the problem becomes urgent
Financial management can feel intimidating, particularly for owners who started businesses because of their expertise in a craft, product or service rather than accounting.
Help is available.
The SBA connects businesses with free or low-cost counseling and training through Small Business Development Centers, SCORE, Women’s Business Centers and Veterans Business Outreach Centers. Its resources include guidance on managing finances, business credit, funding, taxes, marketing, cybersecurity and growth.
SCORE also offers financial resources, templates and mentoring from former CFOs, CPAs and experienced business owners.
The best time to seek help is before cash is tight. An advisor can assist with a forecast, pricing review, lender preparation or financial-statement analysis when the owner still has time to act.
Better money management is not about becoming obsessed with every expense. It is about gaining control over the numbers that determine whether a business can survive, invest and grow.
A company that understands its cash cycle, protects margins, collects invoices promptly, builds reserves and reviews financial statements regularly is better prepared to hire, market, expand and withstand shocks.
In small business, growth is not only a sales question. It is a money-management question.
FAQs
What is the most important money-management skill for small-business owners?
Cash-flow management is often the most urgent skill. Owners should know when money will arrive, when obligations are due and whether the business will have enough cash for payroll, suppliers, taxes and debt payments. Profitability matters, but a profitable company can still face trouble if cash arrives too late.
How often should a small business review its finances?
Review bank balances, unpaid invoices and near-term cash needs weekly. Review financial statements, budget performance, margins and debt monthly. Revisit pricing, forecasts and major growth decisions at least quarterly.
What are the three most important financial statements?
The three core statements are the profit-and-loss statement, the balance sheet and the cash-flow statement. Together, they show profitability, assets and liabilities, and actual cash movement. SCORE says each provides a different part of the business’s financial story.
Should I keep business and personal money separate?
Yes. Use a dedicated business bank account and business payment methods. Separation improves recordkeeping, tax preparation, financial clarity and the ability to evaluate whether the business is profitable. The SBA includes opening a business bank account among its key startup and management steps.
How much cash should a small business keep in reserve?
There is no single answer. A useful starting goal is one month of core operating expenses, then two months, then three months or more depending on the business’s seasonality, customer concentration, debt, fixed costs and income volatility.
Why is revenue different from profit?
Revenue is total money earned from sales. Profit is what remains after direct costs, operating expenses, taxes and other obligations. A business can have high revenue but little or no profit if its costs are too high.
How long should a business keep financial records?
The IRS says businesses must keep records as long as needed to prove income, deductions and other tax-return items. It specifically says to keep employment-tax records for at least four years. Retention periods can vary by circumstance, so owners should consult a tax professional for their situation.
Where can I get help with small-business finances?
The SBA offers links to free or low-cost counseling and training through SBDCs, SCORE, Women’s Business Centers and Veterans Business Outreach Centers. SCORE also offers financial templates and mentoring from experienced professionals.